October 10, 2026 · Financing
What I'd Tell a First-Home Buyer About a $950k Off-the-Plan Townhouse
Off-the-plan settlement risk can hurt more than a market drop. Here's how to think about valuation gaps, first-home grant rules, and renting it out later.

A reader asked me whether $950,000 is a sensible price for a new four-bedroom townhouse in Woodville, South Australia. She's a first-home buyer, plans to live in it for a while, then rent it out, and she's worried about a market drop.
Here's what I'd tell her over coffee.
The settlement gap most buyers miss
Off-the-plan means you sign a contract for a property that hasn't been built yet. You're buying the plans and the finishes schedule. And a promise. Settlement is the day the title transfers and the bank hands over the loan money.
The bank doesn't lend against the contract price. It lends against its own valuation of the finished property, done close to settlement. Say you contract at $950,000 and the bank values it at $900,000 at settlement. If you're borrowing 80% of the bank's value, that's $720,000. Your total cash requirement becomes $230,000. If you already paid a $95,000 deposit, you still need another $135,000 at settlement.
That's the trap. I've seen this happen more than once when I managed rentals and talked to owners who bought off-the-plan. They budgeted for the deposit and the stamp duty, but not for a valuation gap. A shortfall of even three or four percent is enough to wreck the numbers.
The grant and stamp duty fine print

South Australia's first-home owner grant and transfer duty relief have a live-in requirement. Transfer duty is the tax you pay when the property title changes hands, and some people still call it stamp duty. I'm not a lawyer, but the general rule is you need to live in the property as your principal place of residence (your main home, the one you actually live in) for at least six continuous months, usually starting soon after settlement.
Rent it out before you satisfy that residency period and the revenue office can claw back the benefit. The same applies if you move overseas before the six months are up. The grant and duty relief are real money, but they attach strings.
Moving overseas changes everything
She mentioned she might move overseas for work. That's a bigger deal than the price. If the lender approved your loan as owner-occupied, leaving the country and renting the place out can trigger a requirement to tell the lender. They might switch you to an investment loan, which often carries a higher rate and different assessment.
Then there's capital gains tax. CGT is the tax on the profit when you sell an investment property. If you live in the place first and establish it as your main residence, you may get a partial exemption when you sell later. Move overseas and rent it out, and the timing of that move decides how much exemption survives. I'd talk to an accountant who knows the six-year absence rule before signing anything.
Market drop risk is real, but secondary
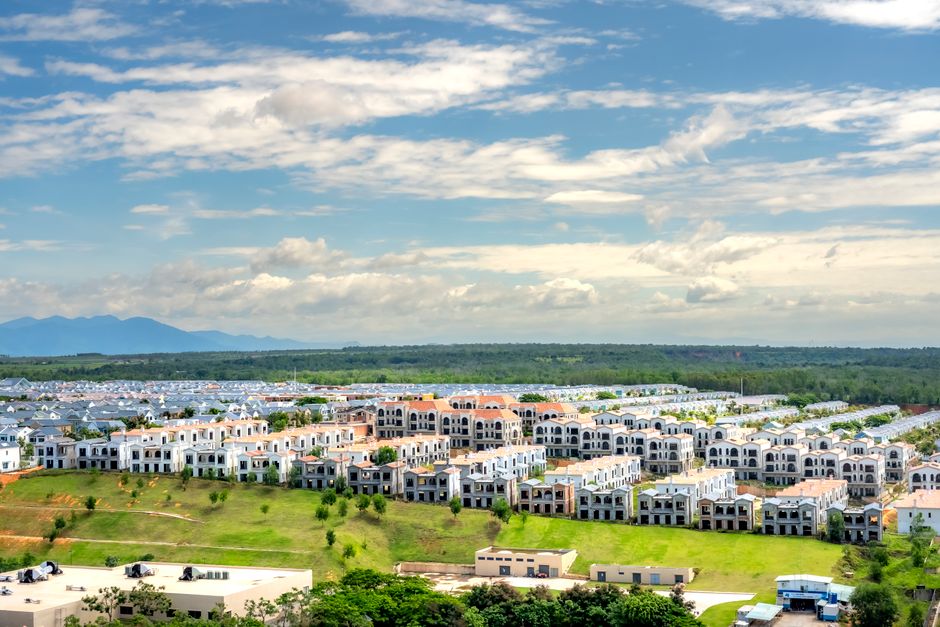
A market drop matters most in the first three to five years, because selling costs and interest eat equity. If you can hold for ten years, a short-term drop is noise, assuming the area keeps jobs and rental demand. Woodville is in Adelaide's western suburbs. I don't have inside knowledge of its future, but as a landlord I'd look at vacancy rates (how many rental properties sit empty) and infrastructure spending. I'd also check how many similar townhouses are going up nearby.
A four-bedroom townhouse appeals to families, which helps rental demand. But townhouses on small lots have less land value than houses, so long-term growth depends more on location scarcity and less on the size of the building.
What I'd check before signing
Get a copy of the grant conditions and read the residency clause. Ask the lender how it handles off-the-plan valuations and what happens if the valuation comes in low. Talk to an accountant about CGT and the main residence exemption, especially if an overseas move is even possible.
The $950,000 sticker price is the least interesting number here. What actually decides whether this works is what happens between signing and settlement, and what you signed away in the fine print to get the grant.