October 6, 2026 · Financing
What an $84k Income Really Buys in Auckland
A retired property manager breaks down what an $84k income and $152k savings can really buy in Auckland, and how to structure deposit, emergency fund, and share sales.
I had a young bloke email me last week. Eighty-four thousand a year, he said. A hundred and fifty-two grand in a mix of cash and shares. Wants a two-to-three-bedroom low-maintenance place within an hour of Auckland's CBD. He asked me if he could do it. Short answer: yes, but not the way he's picturing it.
What the Bank Will Actually Lend You
Banks don't care how much you've saved. They care about your income. On eighty-four thousand a year, a solo buyer can usually borrow somewhere between four hundred and fifty and five hundred thousand. That's five to six times income, which is the rough ceiling for most lenders in New Zealand right now. It's not a hard rule. Your actual number depends on your debts and your credit card limit, plus whether you have any dependants.
So let's say the bank gives you four hundred and seventy-five thousand. Add your deposit, and that's your budget.
You don't want to tip your whole savings into the property. You need a deposit, an emergency fund, and enough for the purchase costs. If you put down a hundred thousand, you're looking at a purchase price around five hundred and seventy-five thousand. Put down a hundred and twenty, and you're at five hundred and ninety-five. That's the realistic ballpark.
What That Buys in Auckland
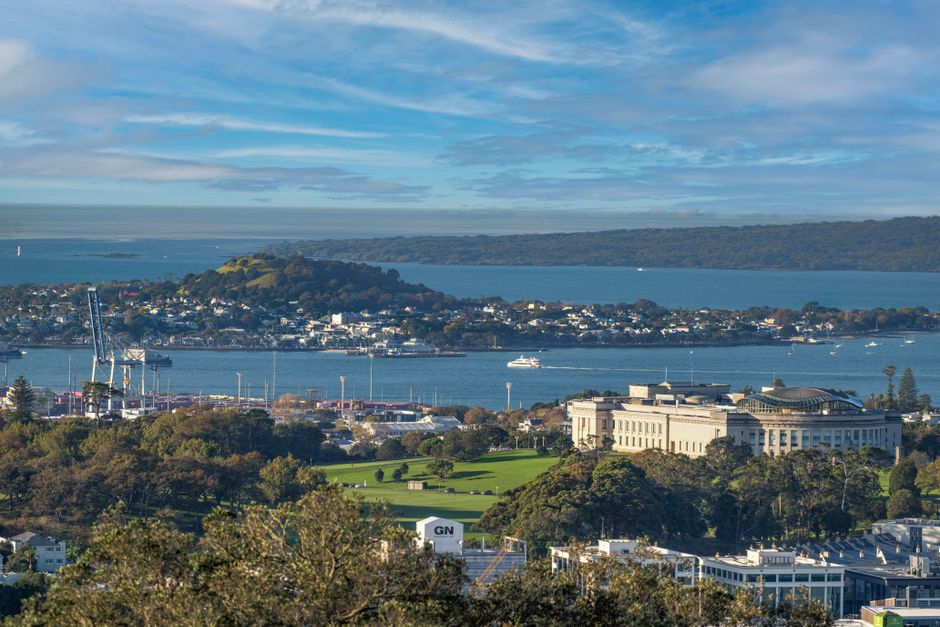
Here's the hard truth. A standalone two-to-three-bedroom brick-and-tile home with no body corporate, within an hour of the CBD, is out of reach at six hundred thousand. Those places are going for well over seven hundred in most suburbs, often more. A body corporate is an owners' association that manages shared areas in a unit-title development. You pay an annual fee. Many first-home buyers want to avoid that fee, but it also pays for maintenance you'd otherwise do yourself. At six hundred thousand, your choices are a two-bedroom townhouse or unit, probably in west or south Auckland. Some will have a residents' society instead of a full body corporate. That's a lighter version where owners split common costs informally. You'll still pay something each year for shared driveway repairs or a garden. The commute will be forty to fifty minutes on a good day.
That doesn't mean it's a bad buy. A low-maintenance unit is a smart first step. You build equity and learn what you can tolerate, then you trade up later. I've watched dozens of first-timers do exactly that.
Structuring Your Deposit and Emergency Fund
Aim for a twenty percent deposit. On a six-hundred-thousand purchase, that's one hundred and twenty thousand. If you only have ten percent, the bank will charge you a low-equity margin. That's an extra interest rate loading on top of the standard rate. It can add thousands to your yearly payments. On top of that, low-equity buyers often pay a higher interest rate from the start. It's worth waiting an extra few months to get to twenty percent.
Keep at least twenty to thirty thousand dollars in liquid cash after settlement. Liquid means money you can access in a day, not tied up in term deposits or shares. You'll need it for rates and insurance, plus the first surprise repair. A hot water cylinder dies in the first winter more often than you'd think.
Now, the shares. Don't sell them too early. A mortgage broker can get you pre-approved using screenshots of your share portfolio. Pre-approval means the bank has agreed to lend you up to a certain amount, subject to conditions. You only need to sell the shares when you've found a house and the bank needs the cash for the deposit before settlement. That can be six weeks later.
But check the timing on employee shares. If your company only allows you to sell during certain buyback windows, you need to line that up with your settlement date. I've seen a buyer lose a property because the share sale cash didn't clear in time. The vendor walked, and the buyer had to start the search again.
A Boarder Changes the Math

If you're open to it, take in a boarder. The bank can count some of that income toward your borrowing capacity. A flatmate paying two hundred a week in rent adds about ten thousand a year to your income. That pushes the borrowing ceiling up by fifty or sixty thousand. Suddenly a standalone brick-and-tile place in a better suburb starts to look possible. You have to be comfortable sharing your home, and the lender will want to see a signed flatmate agreement. But it's a legitimate way to stretch your budget without overextending.
The worst thing you can do is rush. Get a broker on the phone before you sell a single share. Find out your actual borrowing number, then go look at what's actually for sale in west and south Auckland. The dream of a three-bedroom brick-and-tile might need to wait a few years. The two-bed townhouse won't.